By Michael A. Jones - PREC* | Royal LePage Kelowna
October 28, 2026 | Market Intelligence
The Bank of Canada has raised its policy rate by a quarter point. For a buyer already stretching to afford a home, another expense does not need to be enormous to change the decision.
Some buyers will lower their ceiling. Some will negotiate harder. Others may put the search on hold. A buyer who can purchase without a mortgage does not face that same borrowing squeeze.
That creates an opportunity worth examining, particularly for seniors with cash available to downsize. It also gives sellers a reason to reconsider the price they expect. Your plans may depend on a particular number. The next buyer's budget does not.
What changed, and who feels it?
On October 28, the Bank of Canada increased its overnight policy-rate target by 25 basis points to 2.50%. It also said further increases could be necessary, while emphasizing that it would proceed carefully. That is a possibility, not a promised sequence of hikes.
The effect on a household depends on its mortgage:
- Variable rate, adjustable payment: a change in the lender's prime rate can affect the mortgage rate and payment, according to the contract.
- Variable rate, fixed payment: the payment may initially stay the same while more goes toward interest and less toward principal. Contract provisions, including trigger points, still need attention.
- Existing fixed-rate term: the agreed rate does not automatically change because of today's announcement. Renewal brings a new decision.
- A new fixed-rate quote: do not simply add 0.25 percentage points. Fixed mortgage pricing is influenced by bond yields and lender pricing, rather than mechanically following the Bank's announcement.
FCAC explains the different mortgage structures, and TD explains the bond-market connection. Before changing your buying plan, get an updated quote and payment calculation for your situation.
Why another $71 a month deserves attention
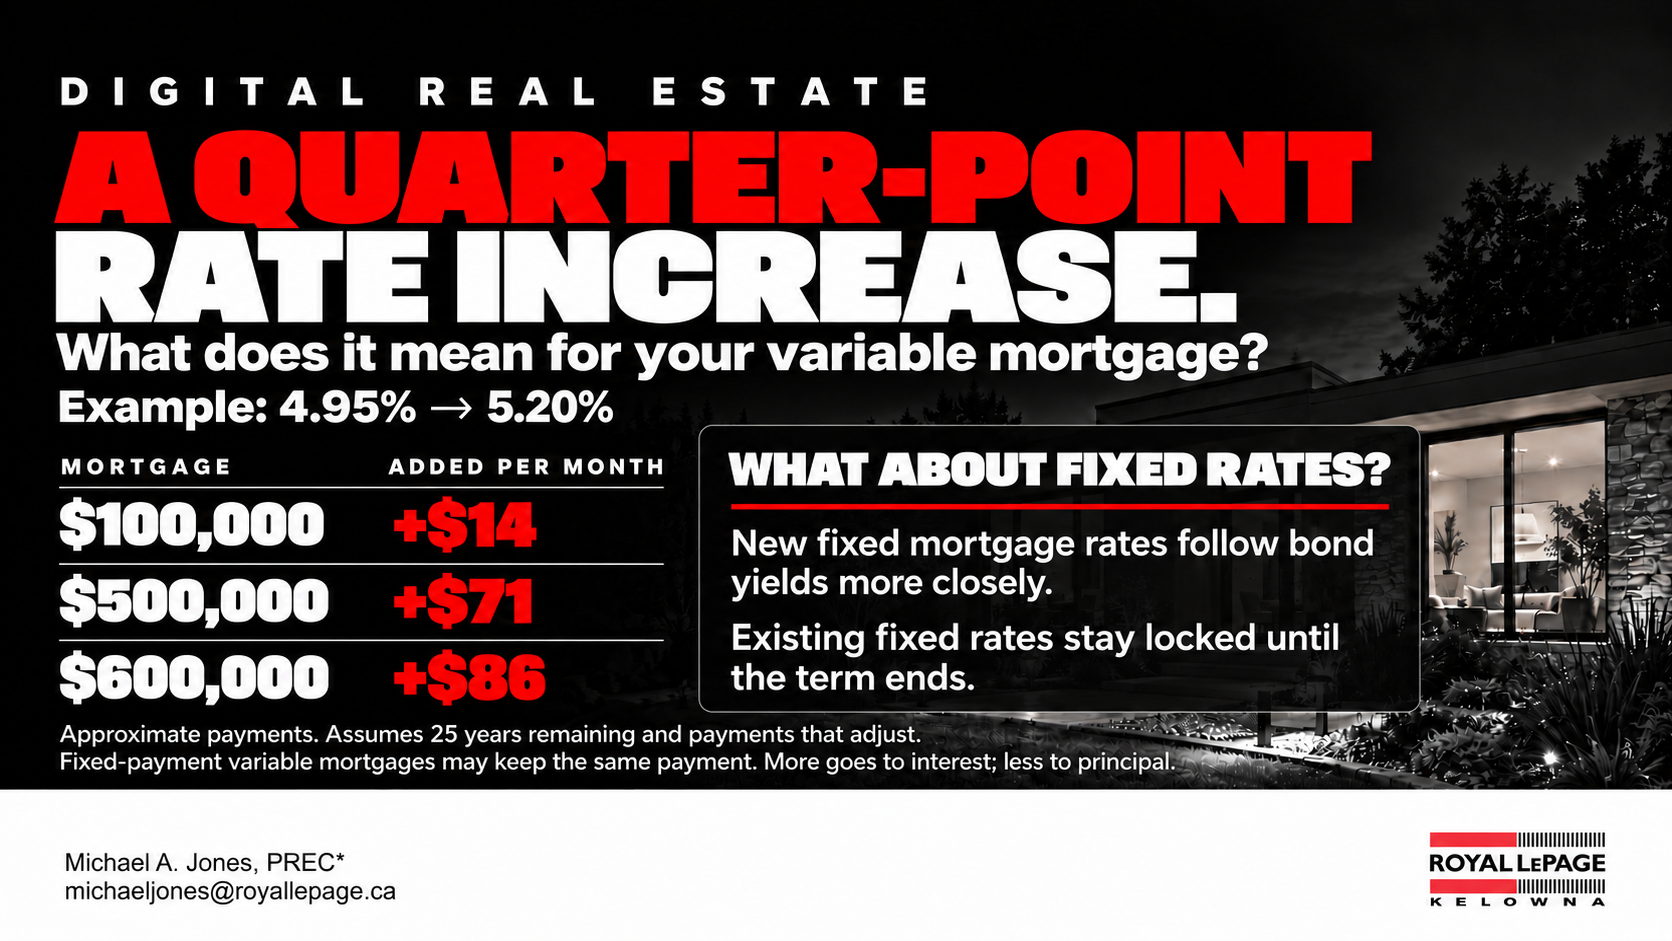
Illustrative mortgage-payment comparison, not a lender quote. Assumes 25 years remaining, monthly payments that adjust, and nominal rates compounded semi-annually. Actual variable-mortgage calculation methods may differ.
Take a $500,000 mortgage balance, not a $500,000 home price. At 4.95%, with 25 years remaining and monthly payments calculated using semi-annual compounding, the payment is approximately $2,893.81. At 5.20%, it is approximately $2,965.21.
That is about $71 more a month. The graphic's rounded $71 figure becomes $852 over a year. Using the underlying unrounded calculation, the annualized difference is closer to $857, assuming the higher payment continues for all 12 months. This is a payment comparison, not a calculation of additional interest alone.
Either way, it is real money. A household has to find it alongside groceries, utilities, insurance and everything else. Different balances, remaining amortizations, compounding methods and payment arrangements produce different results.
Buyers may become more selective
A rate increase can change behaviour before it produces any measurable change in local sale prices.
A buyer who was comfortable at one monthly payment may now want a smaller mortgage. Another may keep the same search range but expect the seller to negotiate. A home needing immediate repairs can become harder to justify when the buyer's cash reserve is already under pressure.
These are plausible responses, not evidence that every Kelowna buyer has stepped back or every neighbourhood will soften equally. The useful question is how buyers are responding to the specific homes competing with yours.
For financed buyers, update the budget before the next offer. Include strata fees where applicable, property taxes, insurance, maintenance and a reserve. Have your lender confirm both qualification and the payment you would actually carry. Those are related questions, but they are not interchangeable.
Cash buyers can negotiate from a different position
A genuinely cash-funded buyer does not need a mortgage to complete the purchase. That can remove one source of uncertainty and give the buyer more flexibility over timing and terms.
If competing financed buyers become more cautious, that flexibility may become more valuable to a seller. A credible offer with funds available and workable completion dates can deserve serious attention even when its price is below the seller's original expectation.
But cash does not entitle anyone to a discount. A well-priced home may still attract competition. Nor does having cash justify skipping an inspection, strata-document review, title review or other appropriate due diligence. Know what you are buying.
The advantage comes from being ready to act on a suitable property, with a clear ceiling and a sound offer. Simply announcing that you are a cash buyer is not a negotiating strategy.
A useful opening for seniors ready to downsize
AI-generated editorial illustration, not an actual property.
For a senior who already has the funds available, this could be a good time to look seriously at the next home. You may be able to buy without taking on the borrowing cost that is making other buyers hesitate.
Focus on the move you want to make: fewer stairs, easier upkeep, manageable monthly costs, access to services and enough room for daily life. A lower purchase price is little comfort if the home will not work for you in five years.
There is one important distinction: equity in an unsold home is not yet cash available to complete a purchase. If your downsizing plan depends on selling first, a more price-sensitive market can affect both sides of the move.
Compare realistic net sale proceeds with the full cost of the next purchase, moving and any temporary accommodation. Include a reserve rather than putting every available dollar into the property. Review the financial and tax implications with the appropriate advisers.
You can explore the wider planning questions in my Okanagan retirement and housing guide.
Sellers: price for the buyer in front of you
This is uncomfortable news for sellers counting on a price the market has not supported. Higher borrowing costs give a stretched buyer less room to accommodate your expectations.
The response should be evidence, not panic. Review recent comparable sales, current competing listings, showing feedback and the offers actually being made. Asking prices show what other sellers want; completed sales help show what buyers have been willing to pay.
If buyers are repeatedly rejecting the same price, waiting without changing anything is still a decision. It may carry additional ownership costs and delay your next move.
Look at the whole offer, too. Price, conditions and completion dates work together. My guide to comparing offers beyond the headline price explains that comparison.
A quarter-point increase does not dictate your home's value. It does give everyone a reason to revisit the numbers. Buyers need a payment they can live with. Cash-funded downsizers may have an opening. Sellers need expectations grounded in today's competition.
Let's work through your buying or selling plan with current numbers.
Explore more mortgage guidance and buying and selling strategy.
General information and personal opinion, not mortgage, financial, tax or legal advice. Payment examples are illustrative, not lender quotes; actual costs and contract terms vary. Behavioural and negotiating effects discussed are possibilities, not forecasts or guarantees of local prices. Confirm financing, available funds and transaction details with the appropriate professionals. Prepared with AI assistance; sources checked October 28, 2026.
*Personal Real Estate Corporation